Table of Contents
Context
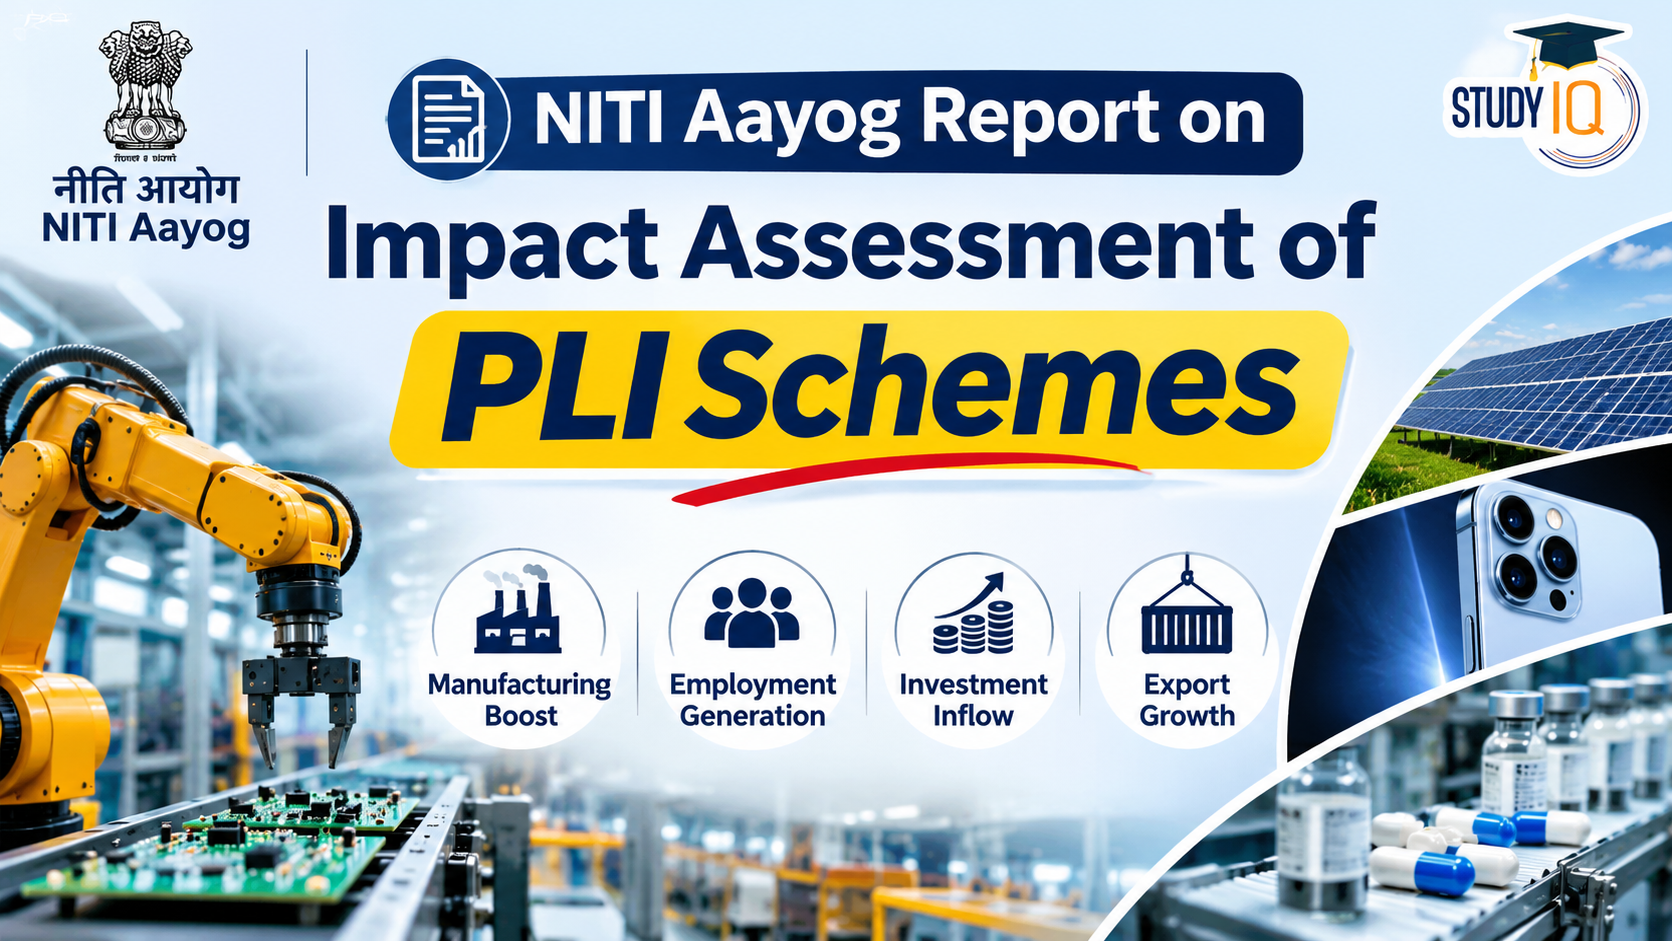
NITI Aayog, with IIM Ahmedabad as knowledge partner, released a mid-course report titled “Impact Assessment of PLI Schemes” evaluating all 14 Production Linked Incentive schemes (₹1.91 lakh crore total outlay) on investment, production, employment, and exports.
What Are the Key Macro-Economic Findings of the Assessment?
- Strong Investment & Output Momentum: Using a 50% mid-course benchmark (at 58% completion of aggregate scheme tenure as of March 2026), cumulative realised investment reached ₹2.40 lakh crore (76% of the ₹3.15 lakh crore target), while cumulative production/sales stood at ₹22.66 lakh crore (64% of the ₹35.37 lakh crore target).
- Lagging Employment Creation: Cumulative employment stood at 8.49 lakh jobs, achieving only 28% of the full-tenure target of 30.18 lakh jobs, reflecting capital-intensive automation and gestation lags between plant commissioning and full capacity utilisation.
- Outcome-Linked Fiscal Discipline: Cumulative incentive disbursement stood at ₹35,354 crore (18.51% of the ₹1.91 lakh crore outlay), ensuring public funds are released strictly post-verification of incremental sales and investment milestones.
- High-Performing Sectors: Nearly 70% of targeted segments are broadly on track, led by Large-Scale Electronics Manufacturing (LSEM) (mobile exports jumped nearly nine-fold to ₹2 lakh crore in FY25 while imports fell 77%), Bulk Drugs & Pharmaceuticals (turning a ₹1,930 crore API trade deficit in FY22 into a ₹2,280 crore surplus in FY25), Drones (seven-fold turnover growth), and White Goods (AC compressor capacity expanded ten-fold to 10 million units).
- Underperforming & Delayed Segments: Advanced Chemistry Cell (ACC) batteries, IT Hardware 1.0 (later revamped as IT Hardware 2.0), and Technical Textiles (only 3.61% fund utilisation) faced delays due to stringent localisation norms, technology deficits, and high eligibility thresholds.
What Structural Challenges Confront India’s PLI Framework?
- Shallow Domestic Value Addition (DVA): Rapid expansion in downstream final assembly (especially in electronics and solar modules) has outpaced upstream component manufacturing, keeping industries reliant on imported sub-assemblies and critical minerals.
- Skewed MSME Participation: High minimum investment caps, incremental turnover thresholds, and complex compliance norms have disproportionately favoured large conglomerates over mid-sized firms and MSMEs.
- Rigid Localisation & Gestation Mismatches: Capital-intensive sunrise sectors (such as ACC batteries and specialty steel) require longer R&D and plant-commissioning cycles, making rigid year-on-year DVA targets difficult to meet without imported machinery.
- Inconsistent Data & Sub-Optimal Utilisation: Variations in firm-level reporting of direct/indirect jobs and net value addition, alongside low fund absorption in select textiles and food-processing sub-categories, limit policy agility.
Way Forward
- Deepen Upstream Component Ecosystems: Pair output-linked PLI incentives with targeted component and capital-goods missions (such as the Electronics Component Manufacturing Scheme) to build indigenous supply chains rather than mere assembly hubs.
- Calibrate Thresholds for MSME Integration: Introduce tiered investment slabs, vendor-development incentives for anchor firms, and simplified HSN/compliance norms to integrate MSMEs into PLI value chains.
- Adopt Realistic Timelines for Sunrise Sectors: Recalibrate gestation periods and phased DVA schedules for high-tech sectors like ACC batteries and solar wafers while supporting industry-academia R&D.
- Strengthen Centre–State & Infrastructure Synergy: Align PLI execution closely with PM GatiShakti, Bulk Drug Parks, and PM MITRA Parks through an institutional Centre–State coordination mechanism to resolve land, power, and regulatory bottlenecks.
 San Francisco Declaration 2026: 10 Count...
 India’s ₹37,500 Crore Coal Gasificat...


 WhatsApp